

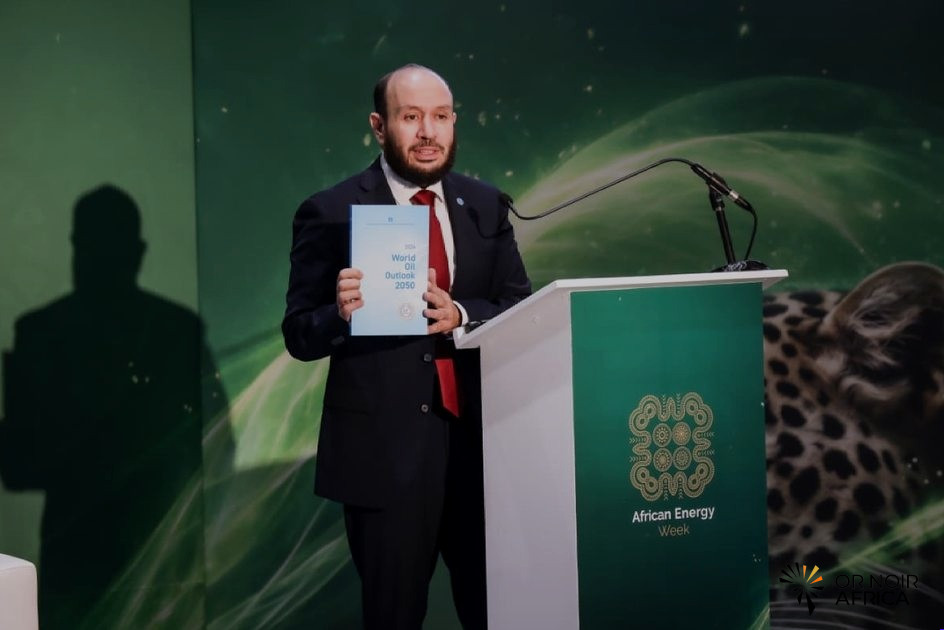
African oil consumption could rise from 4.9 million barrels per day in 2025 to 9.2 million in 2050. This increase of nearly 88% primarily reflects profound demographic and economic transformation. It places the continent at the heart of future energy balances while raising a decisive question: how can rising demand be converted into productive capacity, jobs and broader energy access?
A trajectory driven by demographics and economic activity
Presented at African Energy Week 2026 in Cape Town, OPEC’s projection forms part of an outlook for strong growth in Africa’s population, from just over 1.5 billion in 2025 to almost 2.5 billion in 2050. Urbanization, industrialization and expanding transport networks are expected to accompany this shift. Demand would therefore rise not only because the number of consumers increases: it would also follow the growth of cities, productive activities and trade.
Transport would account for nearly 60% of the expected increase in oil consumption. Other sectors’ needs would come notably from industry, petrochemicals and, to a lesser extent, electricity generation. This distribution is a reminder that energy uses are interconnected. An economy that produces more, builds infrastructure and moves more people and goods simultaneously requires fuels, electricity, networks and logistics services.
The forecast must nevertheless be read as a scenario rather than a guaranteed trajectory. Growth rates, price changes, transport policies, access to financing and technological choices can alter the outcome. Efficiency gains, the electrification of certain uses and the development of alternative fuels will also influence petroleum product consumption.
The challenge is not simply to produce more
Rising demand can attract investment, but does not on its own guarantee better energy security. Several African countries export crude oil while importing refined products. The gap between resources, processing capacity and consumers’ needs reveals a vulnerability: economies remain exposed to international prices, freight costs and supply disruptions.
The response therefore requires a more robust value chain. Exploration and production must be linked to economically viable refining capacity, storage and transport infrastructure, and reliable distribution. Petrochemical development can create additional industrial outlets, provided projects have competitive access to feedstocks, energy and markets. Local value creation will also depend on training, subcontracting and the integration of African companies into major contracts.
This ambition requires trade-offs. A refinery or pipeline network mobilizes substantial capital and needs sustained demand. Decisions must consider market size, crude quality, operating costs and regulatory changes. Regional projects can improve their viability by pooling volumes, infrastructure and markets, but require stable agreements between states and operators.
Energy demand set to diversify
The oil projection describes only part of Africa’s energy future. OPEC also anticipates a doubling of the continent’s natural gas demand. Renewables, including hydropower, wind, solar and biomass, are expected to grow. Globally, electricity generation would increase substantially by 2050, with a growing contribution from wind and solar.
This diversity does not remove the need to plan energy systems. New renewable capacity requires grids, storage and dispatchable resources to balance generation. Gas can meet certain industrial and power needs, while petroleum products will retain a role in transport and several economic activities. National strategies will need to avoid treating these resources as isolated choices and build trajectories suited to each country’s needs and means.
The climate issue remains central. Growth in oil consumption entails emissions risks and the possibility of assets losing value if global demand changes faster than expected. Conversely, neglecting mobility, cooking, electricity and industrialization needs can prolong access deficits and limit competitiveness. Planning must therefore reconcile supply security, cost control, emissions reductions and universal access.
Turning projections into verifiable decisions
For governments, the challenge is to translate scenarios into measurable policies: what share of needs will local production cover? Which refining capacities will truly be competitive? Which investments in grids and transport will reduce costs for households and businesses? And what role will low-carbon solutions play?
Investors, meanwhile, will need predictable rules, balanced contracts and reliable market data. The strongest projects will be those based on demonstrated demand, available infrastructure and tangible local benefits. Local content objectives will gain credibility if accompanied by training programs, realistic schedules and published indicators.
The figure of 9.2 million barrels per day encapsulates both a market opportunity and a governance challenge. Population growth will make energy needs more visible, but the quality of investment choices will determine who benefits. For Africa, the challenge will not simply be to accommodate higher consumption: it will be to build a system capable of supplying the energy needed for development while limiting dependence, strengthening local capabilities and preparing for diversification of the energy mix.
Have any thoughts?
Share your reaction or leave a quick response — we’d love to hear what you think!
-
 0
-
0
-
0
-
0
-
0
-
0





