

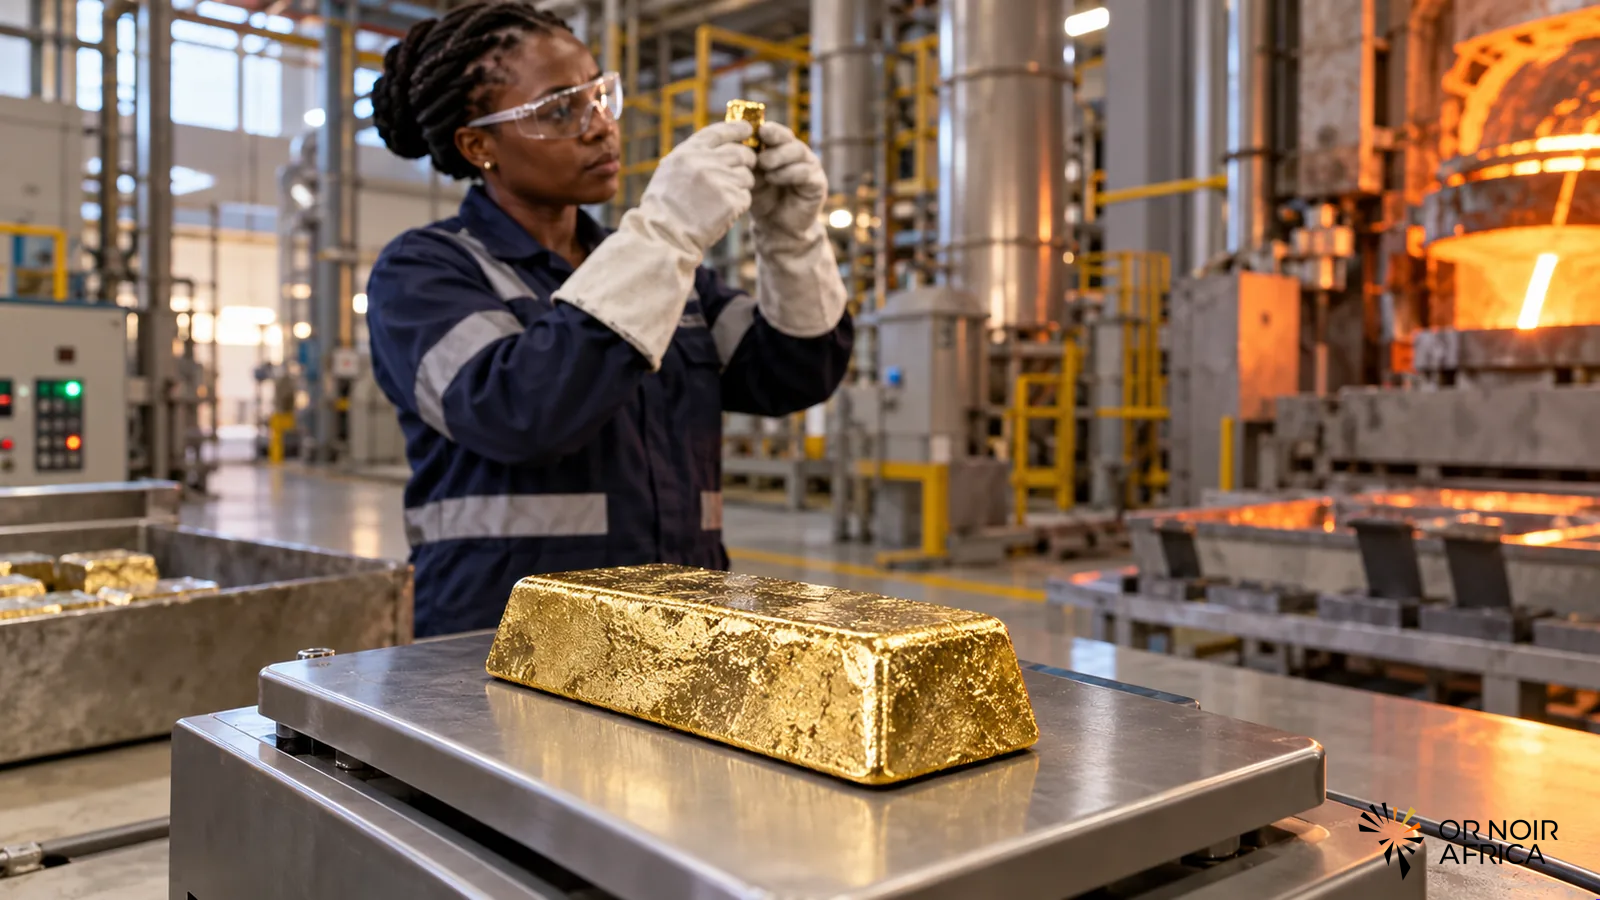
West Africa wants to retain a larger share of the value generated by its gold. Burkina Faso has just inaugurated its first national refinery, Mali is building a facility with a Russian partner, and Côte d’Ivoire is preparing refining operations associated with a new state-owned company. However, capacity announcements alone will not automatically win over major mining groups. For these operators, choosing a refinery involves bullion quality, gold traceability, compliance with buyers’ requirements and smooth payments.
The regional strategy addresses a longstanding question: why do producing countries still export much of their gold in a relatively unprocessed form, while refining and marketing often take place elsewhere? A local refinery can give governments better information on flows and create technical activities. It can also support the formalisation of artisanal gold and improve oversight of the metal’s origin. These objectives are real, but depend on effective use of the facilities.
Three national paths
In Burkina Faso, the RAFFINOR-BF facility was inaugurated in Ouagadougou on 28 September. The announced investment exceeds CFA 11 billion. Its first phase is designed to process up to 164 tonnes a year, with ambitions to increase capacity over time. In Mali, the national refinery project associated with Yadran targets annual capacity of 200 tonnes and provides for majority state ownership. In Côte d’Ivoire, SIMEP is preparing a facility expected to start operations in the first half of 2027, with an announced eventual capacity of 100 tonnes.
These projects are at different stages. An inaugurated facility is not necessarily already running at its rated capacity; a site under construction is not yet producing; planned capacity remains a projection until equipment has been tested and supplied with feedstock. The gap between theoretical capacity and actual throughput is a key indicator when assessing each project’s performance.
Feedstock supply is also decisive. In Burkina Faso, the authorities announced national production of 94 tonnes for the previous year, compared with initial refining capacity of 164 tonnes. This does not necessarily mean the plant will lack material: production estimates may change, artisanal gold may be captured more effectively and regional volumes could be sourced. It does show, however, that industrial capacity must be considered alongside collection strategy, supply contracts and commercial markets.
Trust is built throughout the compliance chain
International mining groups sell their production to buyers who require documented controls. Product purity is one criterion, but only part of the system. Buyers and banks also examine the origin of shipments, due diligence procedures, anti-corruption measures and the ability to track the metal from mine to bullion. International standards and accreditation therefore provide a common language between producers, refiners and markets.
For a new refinery, the challenge is to demonstrate that its standards, audits and traceability systems meet customers’ requirements. Without that recognition, companies may hesitate to change established arrangements even when the facility is close to the mine. Transition costs, insurance, settlement times and access to financial services all influence their decisions.
This reluctance does not mean local refining offers operators no benefits. Rather, it shows that a regulatory obligation or political ambition is insufficient to create a liquid market. Ghana offers an example of an intermediate approach: its GoldBod has combined the Gold Coast refinery with the operational and commercial expertise of Rand Refinery, which is already recognised in international markets. In Côte d’Ivoire, SIMEP’s association with partners specialising in trading, collection and international standards demonstrates similar attention to the conditions for market access.
From industrial capacity to local value
A refinery can retain some processing stages locally, generate more accurate data on flows and strengthen taxation of the sector. However, it does not automatically capture the largest margin in the chain. That margin also depends on purchasing, financing shipments, secure logistics, insurance, trading and buyer networks. Governments will need to specify which activities they wish to localise and measure benefits beyond tonnes processed.
Supporting infrastructure also matters. Refining requires reliable electricity, water, security systems, competent laboratories and chemical management systems. In a region where industrial and energy costs can be high, a facility’s competitiveness will depend on equipment utilisation and its ability to process different categories of shipments without compromising compliance.
The three countries therefore face a dual challenge: building reliable facilities and earning the trust of producers and markets. Indicators to watch include actual throughput, the share of artisanal gold brought into formal channels, certifications obtained, payment times and revenue retained locally. If these improve together, regional refining can move beyond political symbolism and become a lasting part of West Africa’s gold industry.
Have any thoughts?
Share your reaction or leave a quick response — we’d love to hear what you think!
-
 0
-
0
-
0
-
0
-
0
-
0





